For decades, there has been article after article regarding Millennials and their income holding them back from various milestones such as paying off student loans, homeownership, and even having children. Now, it appears that not much has changed and Gen Z is feeling the hurt in the wallet as well.

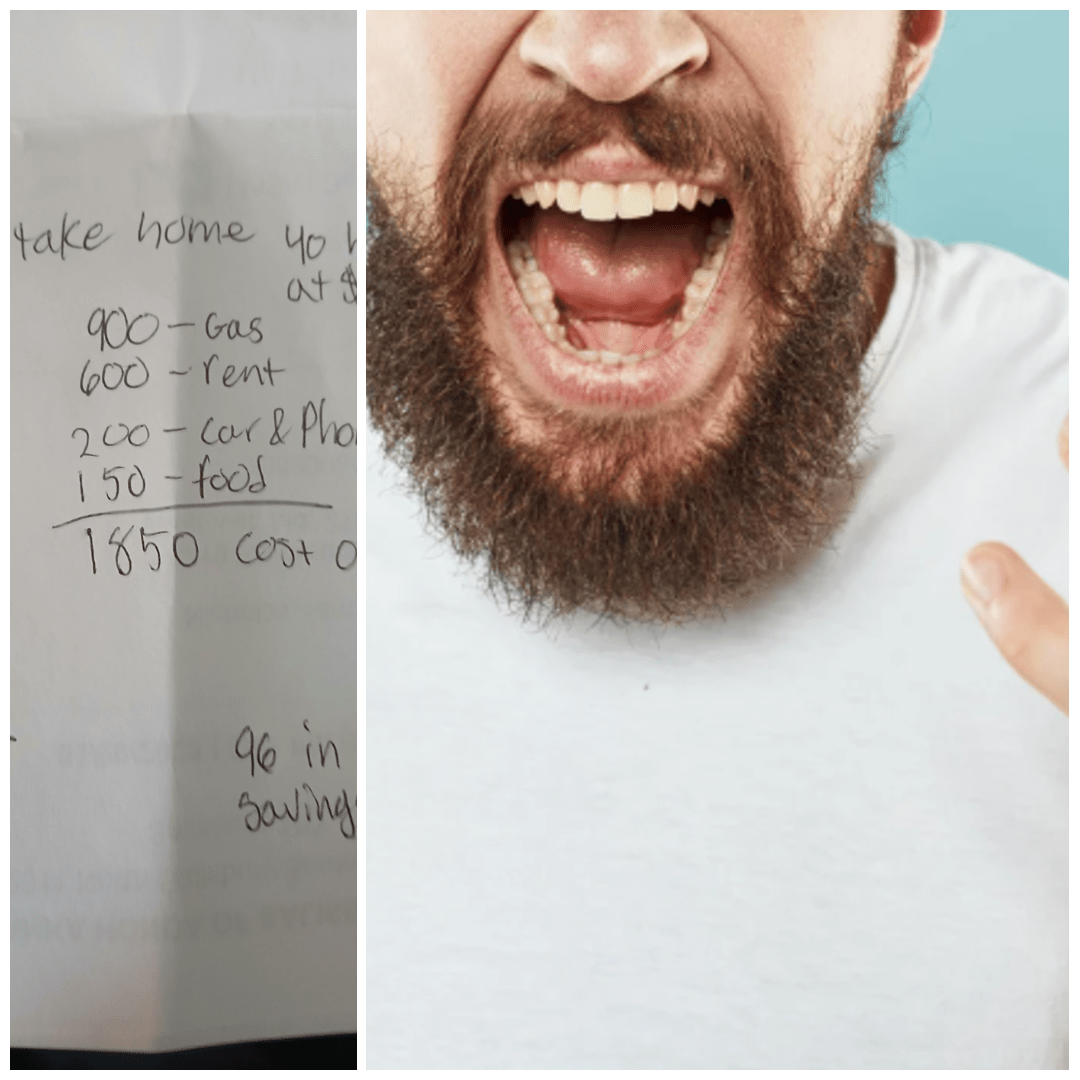
A post on Reddit is making the rounds on the Internet showcasing the budget of a Gen Z worker who is working full time and is still struggling, even though they are living with their parents. After breaking down their monthly earnings with a $16/hour wage, they calculated that after making payments for gas (including fuel for driving his parents and brother around), rent to their parents, food, car payments, and cell phone service, they only take home $96/month in savings. But that little bit of money is one car repair away from disappearing altogether.

The poster continued to share that their parents gave them six months until they had to move out, but that even if they got their raise in four months, it would only be a single dollar per hour more. They also shared that the answer to their problems isn’t “work more hours.”
Empty wallet
Take home pay is becoming less and less as expenses rise year after year. Photo credit: Canva

“I’m showing this to the older generations that say we’re lazy and shit, and I don’t want to hear anything because I’m not allowed overtime and I work 6 days a week,” they wrote.

Other posters shared their thoughts and struggles.

“How do they expect anyone to live on $16/hr when prices have doubled on almost everything?”

“Some states’ minimum wage is still $7.25.”

“Horrible people charging him $600 when he can’t even afford to save.”

“Cost of living is obnoxiously high and wages aren’t nearly high enough to balance out how much it costs to live.”
past due bill
Making bill payments gets harder each year. Photo credit: Canva

While the poster got some advice regarding finding a place closer to his job, investing in a better vehicle, different budget math, and other ways to help make ends meet, the fact remains that Gen Z is falling into the same financial burden that Millennials have long fallen into.

To put things into perspective, the national minimum wage, currently standing at $7.25/hour, was last changed in 2009, back when the oldest Gen Zers were 12 years old. While some states have raised their minimum wage, the lion’s share haven’t raised wages or their raises still wouldn’t make enough difference to help their residents make a living.

Here are some examples using the Massachusetts Institute of Technology (MIT) living wage calculator. Iowa, which has the national limit for minimum wage at $7.25/hour, would require a single person with no kids to make $20.89/hour as a livable wage. Even if you lived in Washington, D.C. which has the highest minimum wage at $17.50/hour, it would require a single person with no kids $25.98 to make ends meet. It should be stressed that those are for folks that live alone without kids, as the cost of living would be even greater should you and your partner have children.

It should also be noted and stressed that the minimum wage was established to help adult workers obtain “purchasing power” for the overall economy, not as a “starter wage” for teenagers and others who are just entering the work force. Its intention was to protect all workers from exploitation from their employers. As the Reddit poster and MIT shows, even $16/hour doesn’t provide much for the modern worker.

As Millennials and Gen Z get older, solidarity will hopefully form and bring about change that will benefit both generations through collective action, changes in economic policy, and life overall.

This article originally appeared in March.
  • Criminal conspiracy to steal used cooking oil shows how trash can become treasure
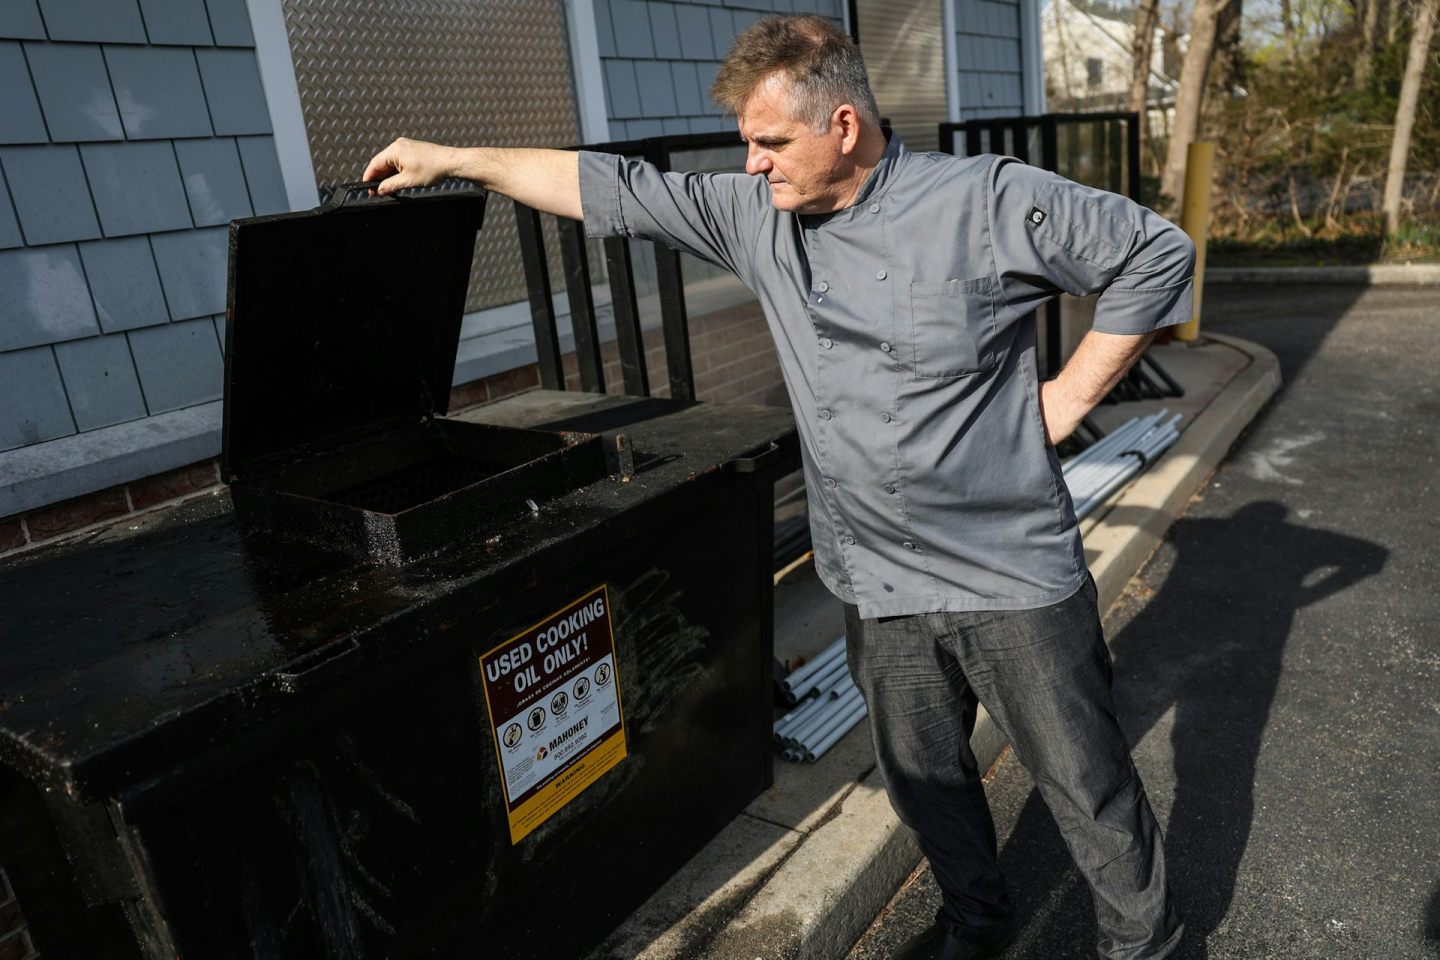
    A restaurant owner looks at a tank for collecting used cooking oil. Steve Pfost/Newsday RM via Getty Images
    ,

    Criminal conspiracy to steal used cooking oil shows how trash can become treasure

    Yesterday’s fryer grease can be tomorrow’s valuable cargo.

    William R. Kenan, Jr. Professor of History and Environmental Studies, Amherst College

    Federal prosecutors recently described an interstate criminal enterprise with all the trappings of organized crime: clandestine warehouses, money laundering and stolen goods transported across state lines. The mid-September 2026 announcement stated that 19 defendants faced charges; two had just pleaded guilty, while the remainder are slated for trial in April 2027.

    The stolen material was not drugs, guns or jewels. It was leftover cooking oil.

    According to prosecutors, members of the group drove trucks to restaurants in 10 states, siphoned used cooking oil from collection tanks and transported it to depots for resale. The alleged motive was simple: Used cooking oil has value. It can be refined into biodiesel. A viscous fluid that the food industry formerly considered garbage has become valuable enough to spur a large-scale criminal operation.

    This oil-theft scheme points to a larger lesson. People tend to think of waste as trash, sewage, slag, manure and other seemingly useless or disgusting substances. But historians, anthropologists and geographers increasingly recognize that “waste” is a category defined by humans. Technologies, markets, laws and cultural assumptions all determine what is discarded, what is kept and why. Waste describes a material’s status, not necessarily its substance.

    As an environmental historian who studies how societies transform nature into commodities, I am also interested in the other side of the process: how materials classified as waste can be converted back into things of value.

    Making matter into ‘waste’

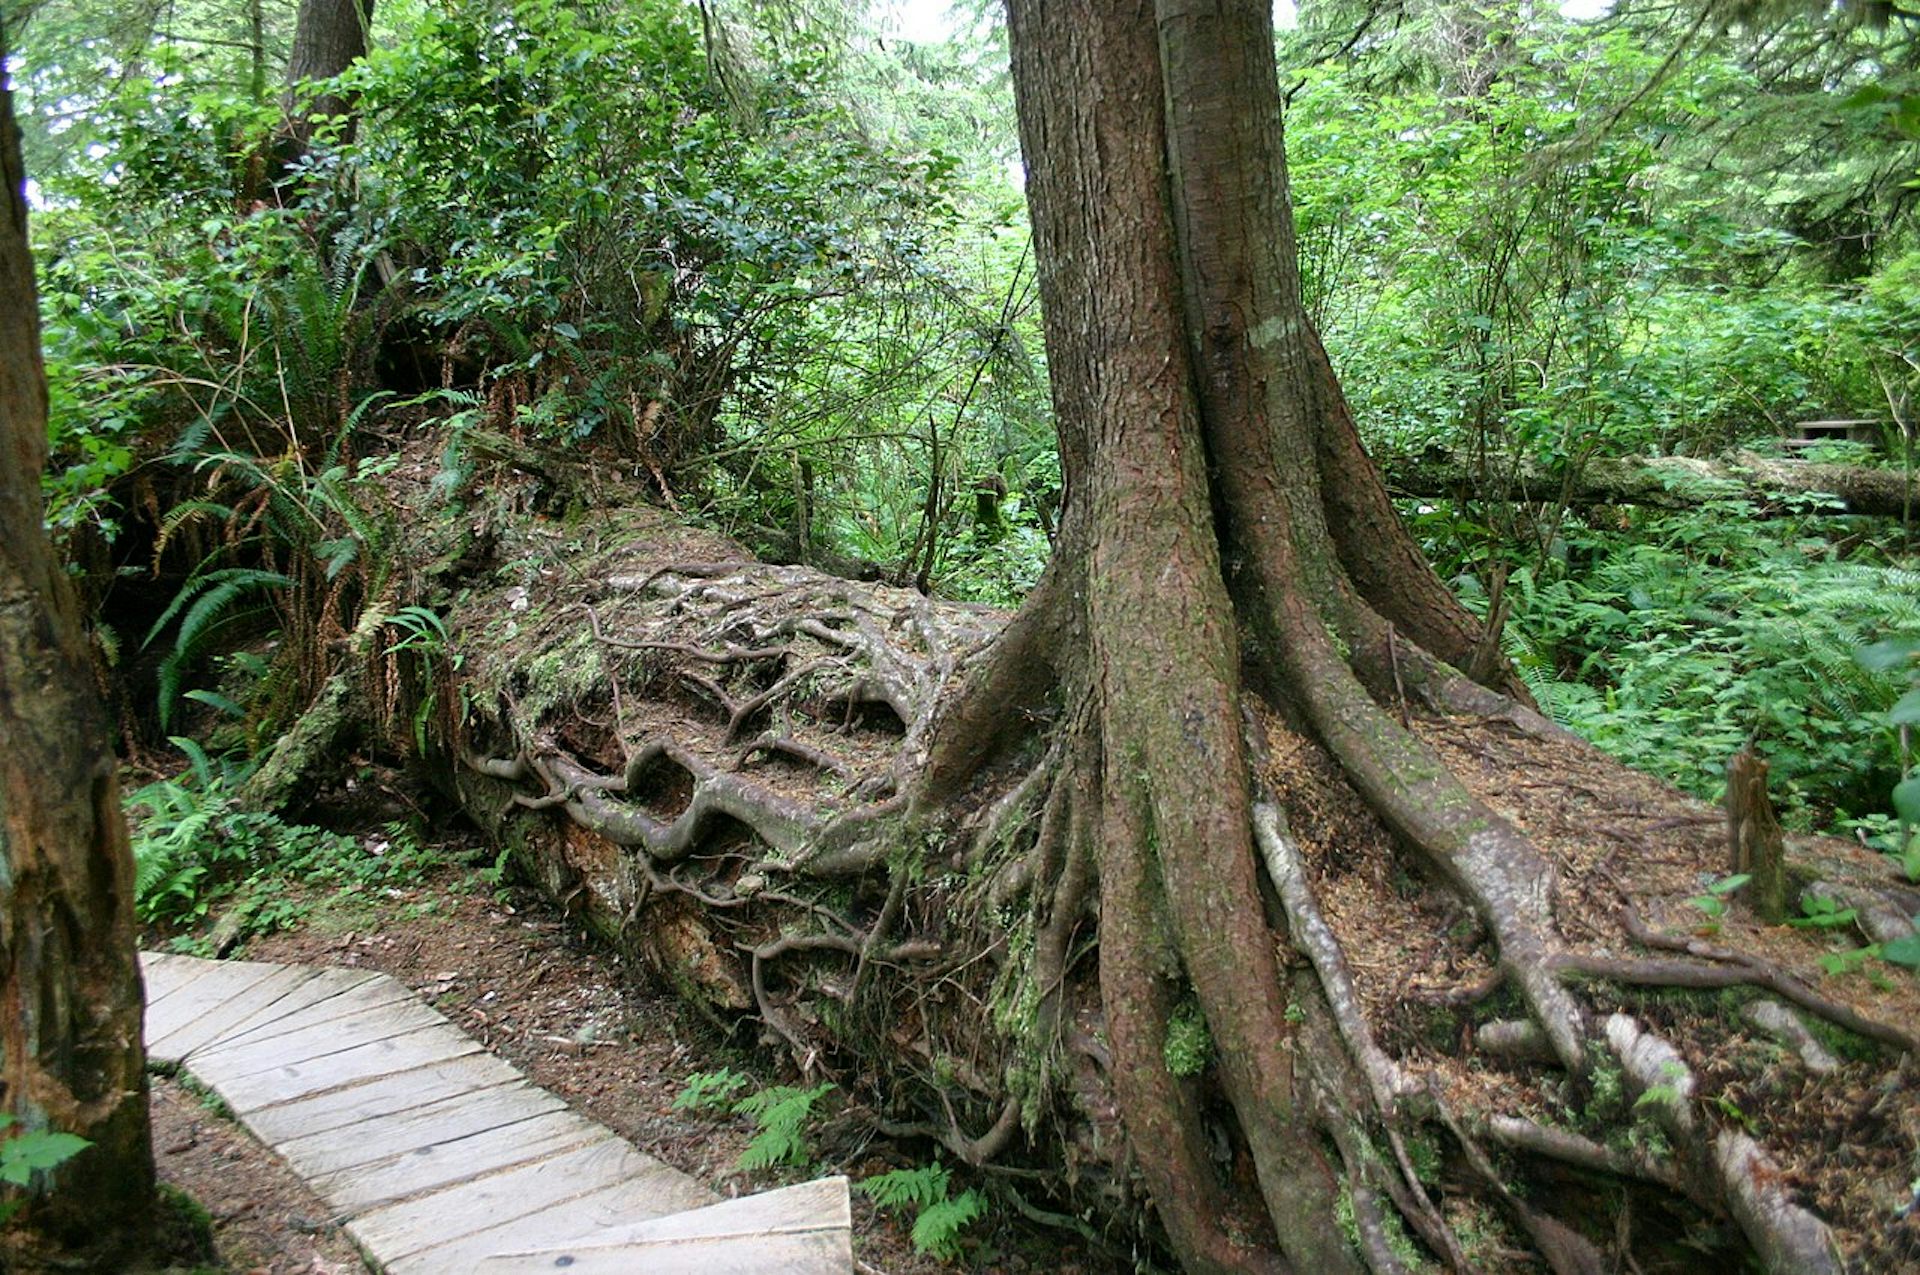
    Nothing in nature is wasted. A fallen tree becomes food for fungi and insects, while its nutrients eventually return to the soil or the atmosphere; animal feces feed creatures ranging from bacteria to dung beetles. In ecosystems, one organism’s leftovers routinely provide for another’s needs.

    Trees of different ages grow from a fallen log.
    A fallen log serves as a nursery for a new hemlock tree in British Columbia, Canada, hence the nicknames nursery log or nurse log. Wing-Chi Poon, CC BY-SA

    Human societies, by contrast, frequently remove unwanted materials from circulation. The question of where those materials go – and whether they remain useless – is part of the history of waste.

    Scholars in a growing field called “discard studies” examine this process. Sociologist Zsuzsa Gille describes different “waste regimes,” the ideologies and concepts that people use to determine what’s valuable and what’s disposable.

    Calling something “waste” does not mean that its physical properties are irrelevant. A toxic chemical can poison a river. But whether people dump, recycle, store or reprocess that substance – and whether they classify it as waste at all – depends on human decisions.

    Industrialization did not invent waste, but it dramatically changed its scale and geography. During the 19th century, factories and processing plants brought raw materials together in unprecedented quantities and consolidated their unwanted residues in the same sites. That concentration created disposal problems. It also generated new incentives to find profitable uses for what industry left behind.

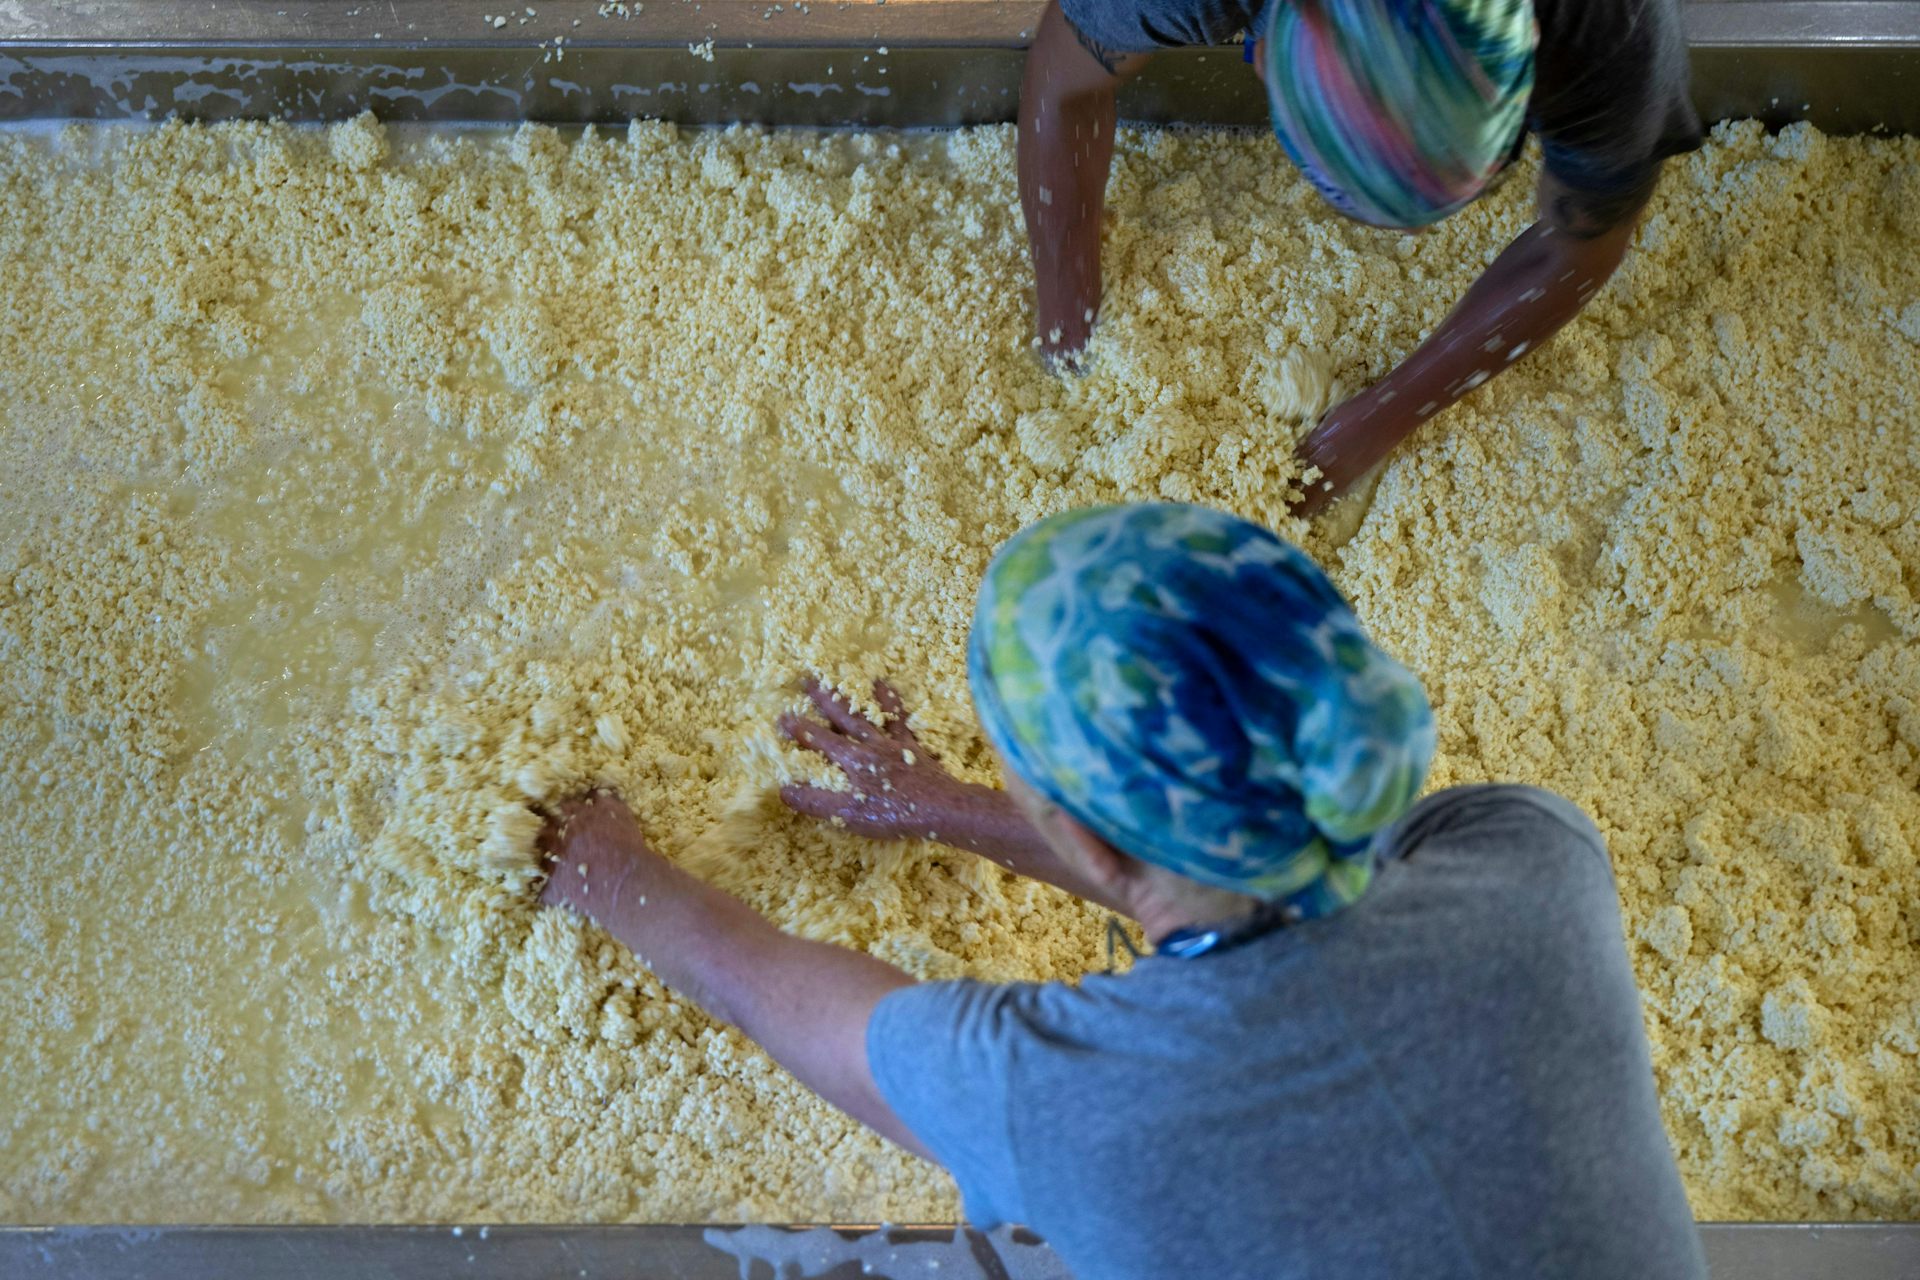
    An overhead view shows people separating milk curds from whey liquid.
    Making cheese involves separating curds from whey. Brendan Smialowski/AFP via Getty Images

    Manufacturing a demand

    Consider whey. Cheesemaking produces extraordinary quantities of the watery liquid left behind after milk coagulates. For much of the 19th and 20th centuries, cheese manufacturers disposed of the whey as an unwanted residue. Dumped into waterways, whey encourages bacterial and algal growth that depletes oxygen and can damage aquatic ecosystems.

    Beginning in the 1970s, ultrafiltration allowed producers to separate and concentrate whey proteins. A troublesome liquid became whey powder, lactose and protein concentrates, all of which can be used in baked goods, infant formula, animal feed and protein supplements.

    Coal-fired power plants provide another example. Coal combustion leaves behind fly ash, a fine mineral residue that companies dumped in landfills or stored in enormous ash ponds. In the 1930s, engineers discovered that fly ash could replace a portion of the Portland cement normally used to make concrete. This new application diverted waste from disposal while reducing demand for energy-intensive cement production.

    There is much to admire in these transformations. Repurposing leftover materials can reduce pollution, conserve resources and lower the amount of material dumped into landfills or waterways. The ecological ideal of “cradle-to-cradle” design rests on precisely this insight. Just as in nature, the output of one process can become the input of another.

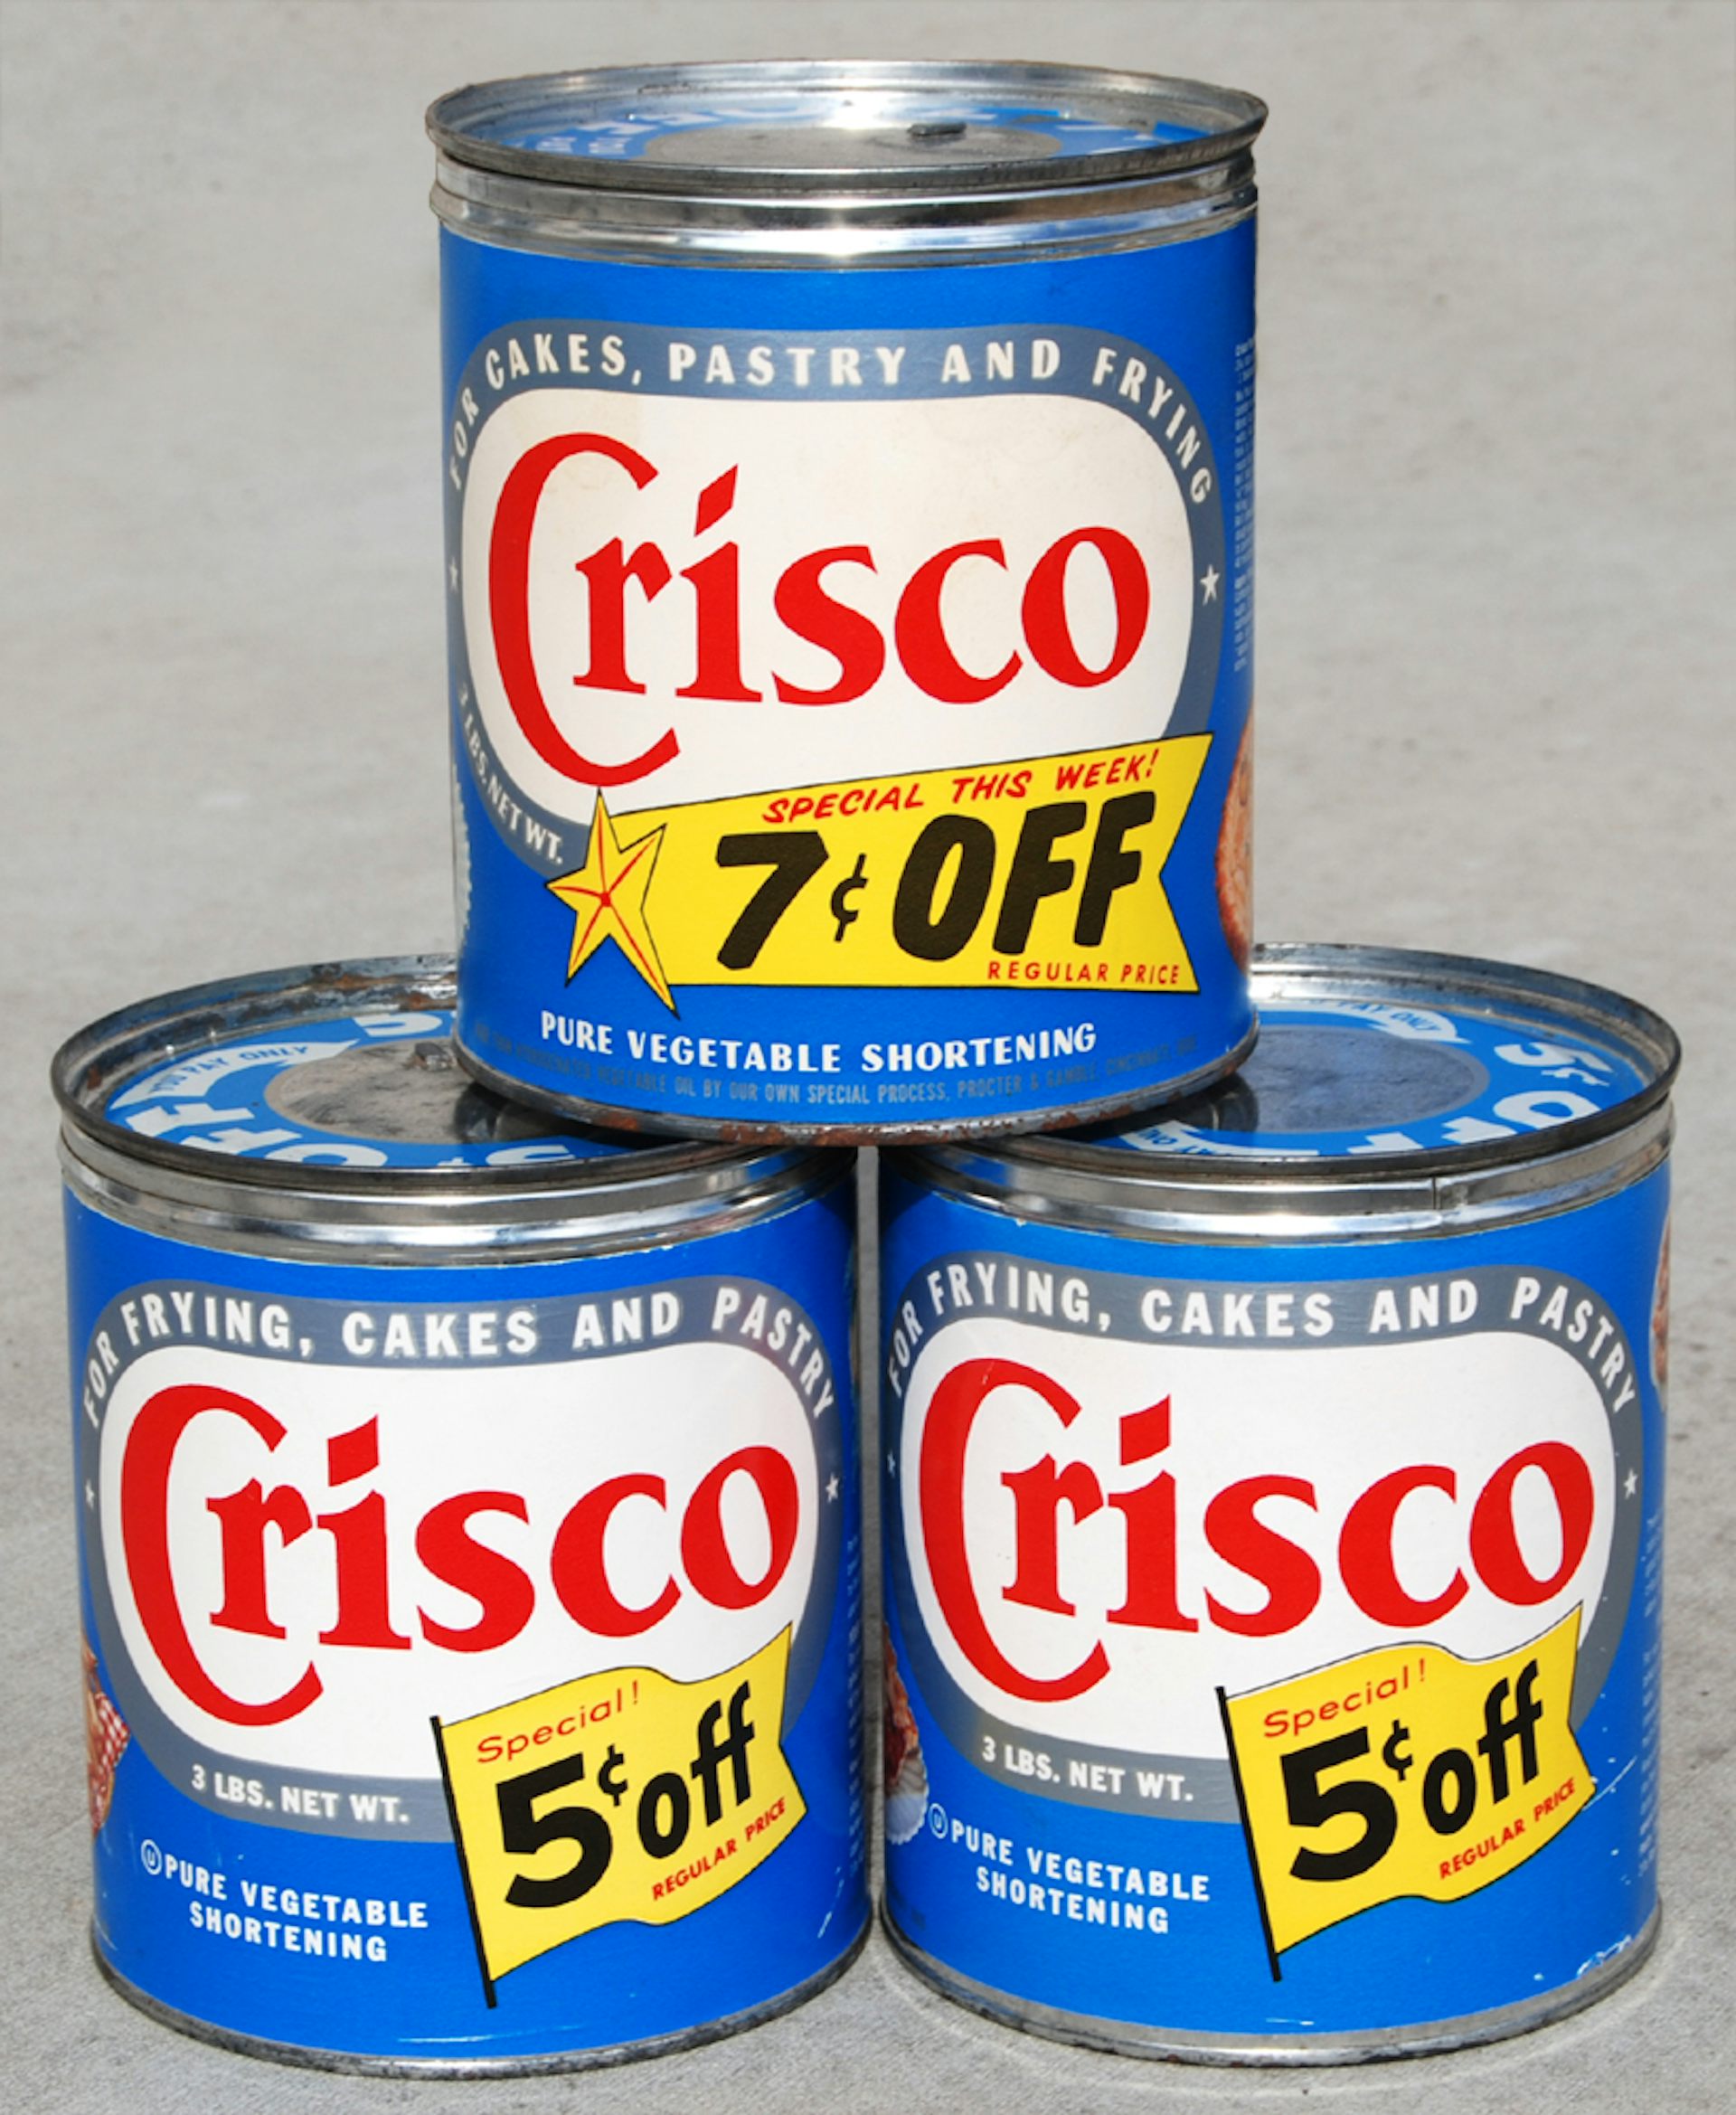
    A stack of three cans labeled 'Crisco.'
    Crisco vegetable shortening was one way to reuse cottonseed oil, a waste product of another industrial process. Roadsidepictures via Flickr, CC BY-NC

    When recycling creates new problems

    Yet finding a market for waste does not necessarily solve the problems that the waste created in the first place.

    Cottonseed provides a striking example. During the 19th century, American cotton growers regarded seeds as an enormous nuisance. Cotton ginning generated mountains of seeds, and many operators simply dumped these unwanted byproducts into nearby waterways, where they accumulated in foul-smelling, decaying masses. The problem became serious enough that Southern states began restricting cottonseed dumping in the mid-1800s.

    Then manufacturers learned to crush cottonseed for oil to be used in soap, cooking and as a substitute for animal fats. They turned the remaining material into fertilizer and animal feed. By the late 19th century, something previously seen as garbage had become the foundation of a major new industry.

    Cottonseed boosters proclaimed a transformation of waste into wealth. In 1911, entrepreneur Luther A. Ransom celebrated cottonseed’s ability to produce “edible oil without olives; medicinal oil without codfish; butter without cows; ice cream without cream; lard without hogs.”

    But manufacturers also sometimes diluted more expensive olive oil and lard with cheap cottonseed oil. Beginning in the early 20th century, the chemical process of hydrogenation allowed producers to turn liquid vegetable oils into semisolid fats suitable for shortening and margarine. Partial hydrogenation also produced artificial trans fats, which were eventually linked to increased cardiovascular risk.

    In 1911, Procter & Gamble introduced Crisco, a vegetable shortening made from hydrogenated cottonseed oil. Consumers could use Crisco in place of lard or butter for frying and baking. Decades before the heart disease risks of partially hydrogenated oils were understood, the company marketed Crisco as an expression of purity and modern food technology.

    The problem was not that cottonseed oil was secretly “waste.” It was that industrial processing widened the gap between what manufacturers knew about a product’s origins and composition and what consumers understood about those attributes. Turning a discarded material into a valuable commodity solved one problem while creating another. Consumers increasingly had to trust manufacturers to tell them what they were buying.

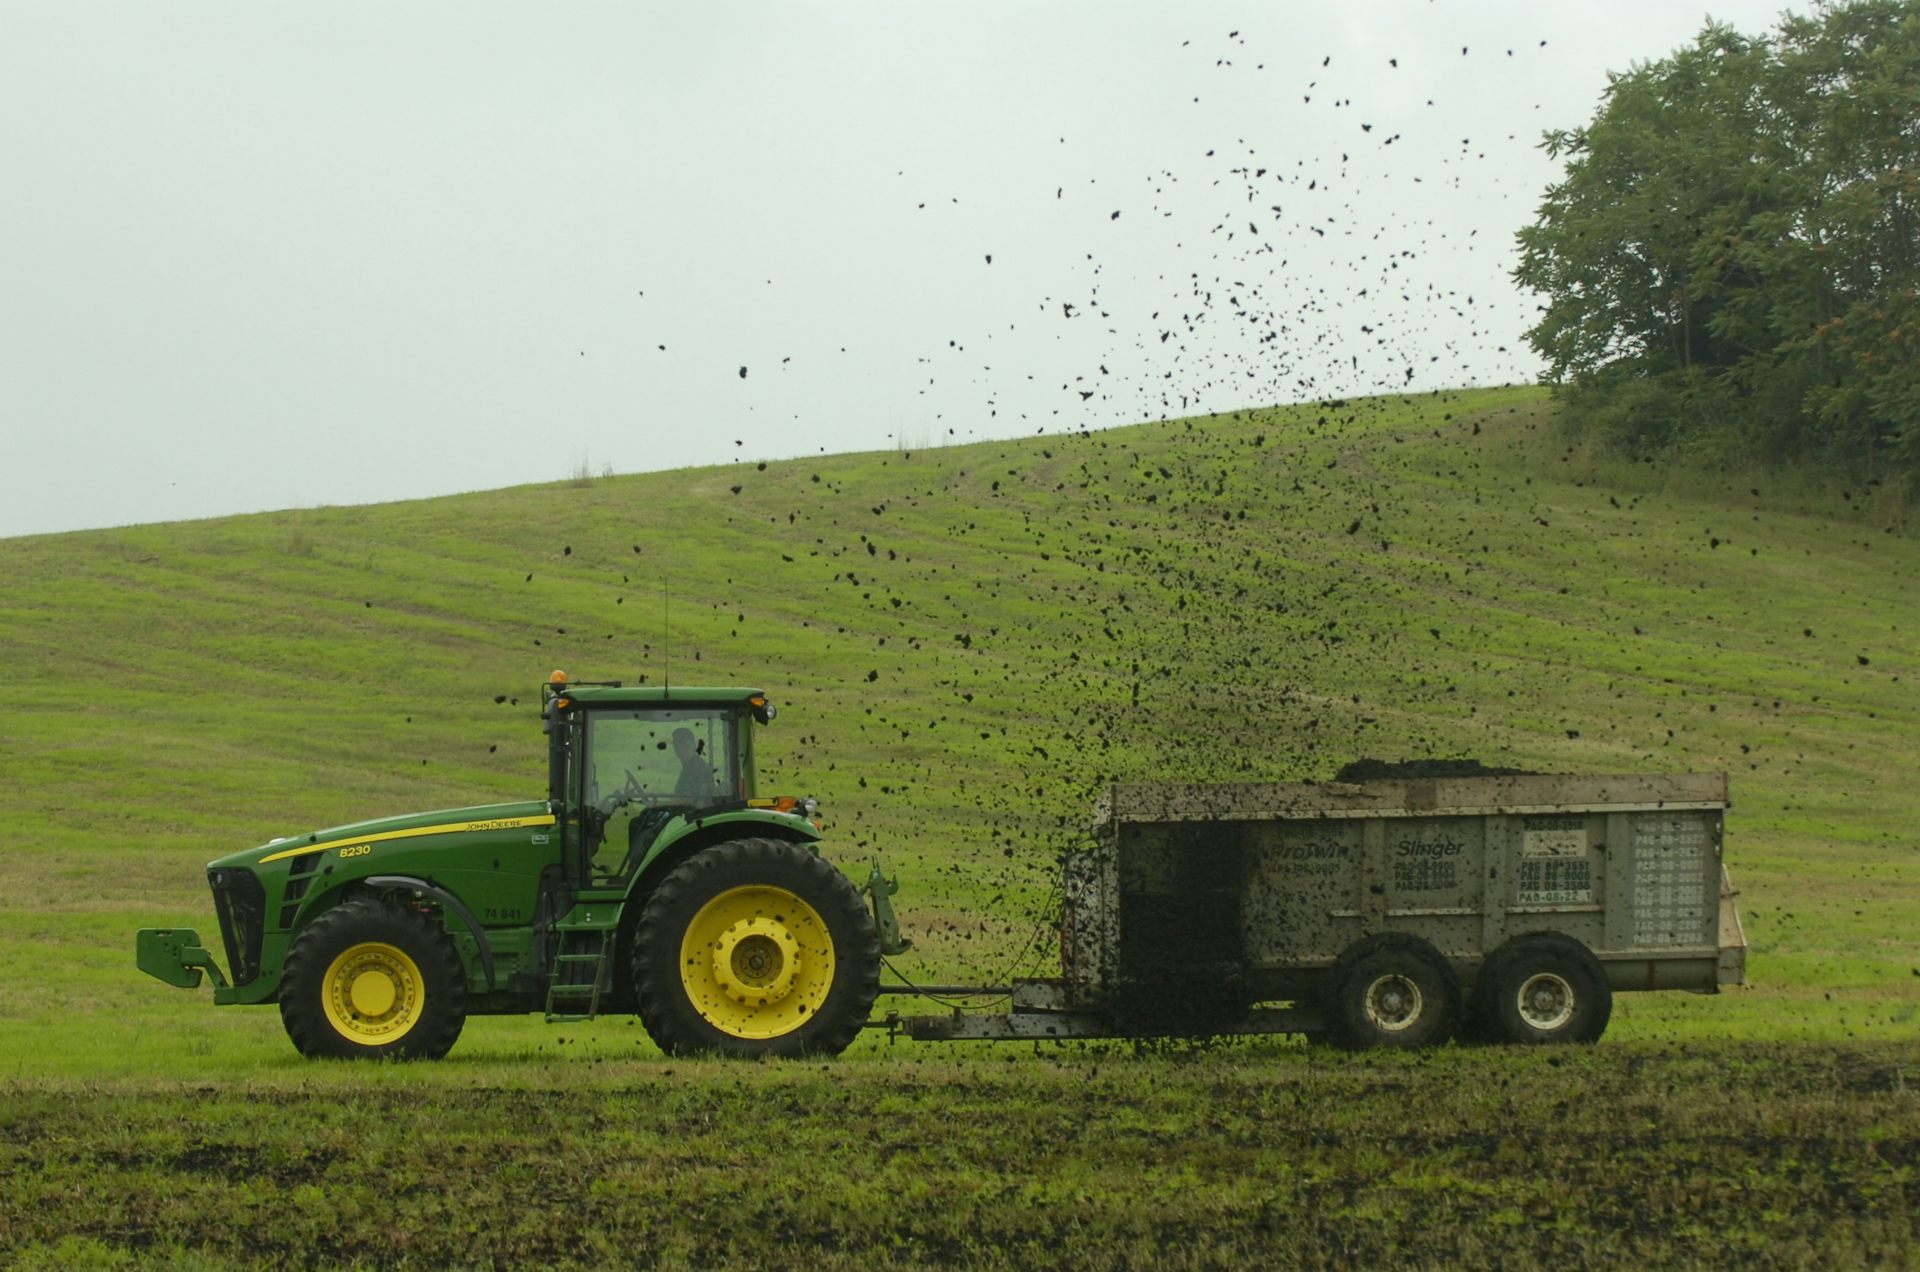
    Sewage sludge presents an even sharper dilemma. Wastewater treatment produces nutrient-rich dregs that can be processed into biosolids and spread on farmland, returning nitrogen and phosphorus to soils. But wastewater also carries contaminants. Researchers have found a group of chemicals known as PFAS – persistent and potentially harmful “forever chemicals” more formally known as perfluoroalkyl and polyfluoroalkyl substances – in some sewage sludge. Their presence raises concerns that a system designed to salvage nutrients can also recycle pollutants.

    A tractor pulls a trailer across a grassy area.
    Spreading sewage sludge on farms can recycle not only helpful nutrients but also harmful toxic chemicals. Ryan McFadden/MediaNews Group/Reading Eagle via Getty Images

    The value of being ‘waste’

    Used cooking oil seems like an almost perfect example of recycling. Refiners turn oil discarded by restaurants and other waste fats into transportation fuel, extracting additional value from crops already grown and oils that have already served their original purpose.

    But government policies regarding clean fuel have made some products that carry the label “waste” economically valuable. Because fuels made from used cooking oil can qualify for financial incentives unavailable to some virgin oils, demand has occasionally pushed prices for used oils above those of newly produced vegetable oils.

    That creates an unusual temptation: mix cheaper virgin oil into used cooking oil – or simply pass virgin oil off as waste. Researchers and regulators have raised concerns about fraud in the rapidly growing international markets for used cooking oil.

    Generating new uses for discarded matter does not eliminate the politics of waste. It can intensify them. Who decides whether something counts as waste? Who profits when something once considered disposable becomes a valuable commodity? And who can verify what a supposedly recycled material actually contains?

    Stolen restaurant cooking oil offers an unexpectedly useful way to think about this problem. The fats and oils inside the tank did not physically change when thieves began siphoning them out. What changed was their status and their value.

    That transformation captures one of the paradoxes at the heart of the history of waste. Matter is never worthless, but assigning it a price does not necessarily make its environmental and social costs disappear.

    Sometimes finding a use for waste solves a disposal problem. Sometimes it merely gives the problem a new price.

    This article originally appeared on The Conversation. You can read it here.

  • Should paper checks be abolished like the penny?
    Photo credit: CSA Images/Getty Images – While Americans are writing fewer checks, they haven’t abandoned this means of payment.
    ,

    Should paper checks be abolished like the penny?

    Billions are still written each year, even as digital payments take over.

    Germany is getting rid of paper checks at the end of 2027. Australia is bidding them farewell by 2030. U.S. President Donald Trump followed up his order killing off the penny with an executive order stopping check writing by the federal government.

    Should the U.S. follow these other countries and broadly eliminate the ability to write checks?

    Years ago, experts predicted that checks would have disappeared by now. However, they are still around, and billions are written each year in the United States.

    Why? The quick answer is that businesses love them. And plenty of Americans still use checks for good reasons. But there is more to the story.

    I am a business school professor and one of the few academics who advocates for the use of cash. While I have long told everyone about the benefits of paper money, I didn’t give paper checks much thought or use them until my mother’s recent death. Then I found myself writing checks to the cemetery, funeral home, gravestone engraver and a host of other places. Plus, I started getting refund checks back from her landlord and insurance companies.

    These experiences made me look more deeply into this form of payment to understand what was happening.

    Fewer checks for bigger bucks

    Every three years the U.S. government runs the Federal Reserve Payments Study by asking banks and credit unions for internal information. This survey tracks everything from how often credit cards are used to the number of checks written.

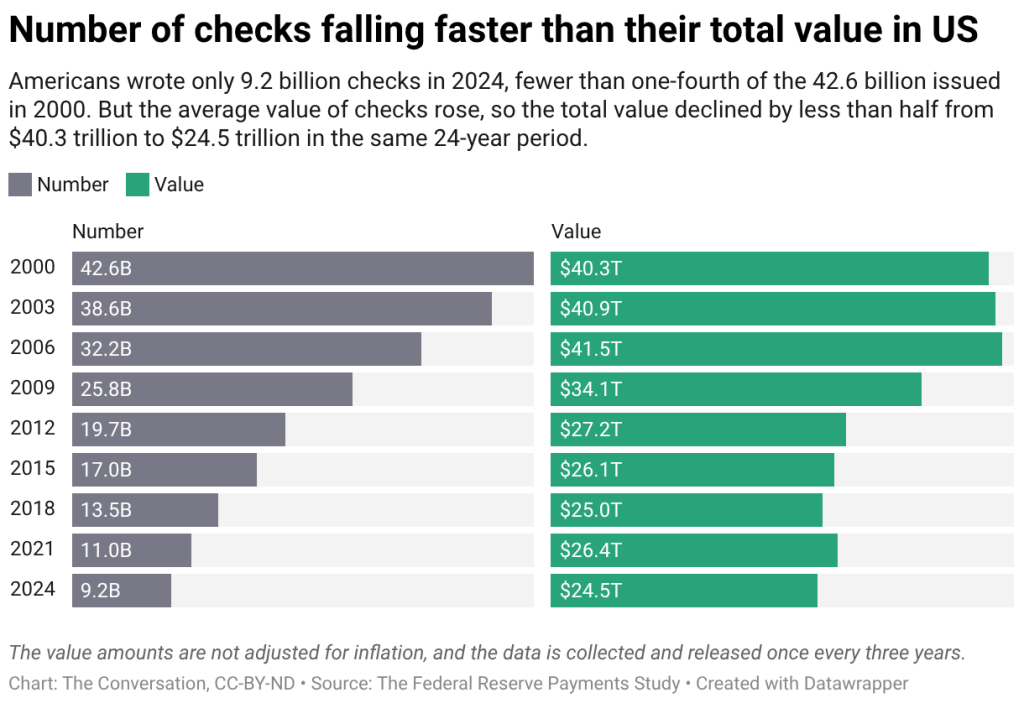
    While check usage has sharply declined in the U.S., a significant number – about 9.2 billion in 2024 – are still written, the data shows. The face value of those checks is probably bigger than you’d expect: more than US$24 trillion, not adjusted for inflation. That is almost as large as U.S. gross domestic product of $29 trillion that year.

    Not everyone can imagine numbers in billions or trillions, so let’s put those figures in more manageable terms.

    A little over 150 checks were written per person in 2000. By 2024, the average had plummeted to 27 checks – slightly more than two per month. However, over that time, the amounts typically scribbled or printed on the face of those checks rose.

    In 2000, the typical check was worth less than $1,000. By 2024, the average amount had more than doubled to $2,600.

    Trends elsewhere are similar. The Bank for International Settlements, which serves as a bank for central banks like the Federal Reserve, has tracked check usage in 25 countries since 2012. Its data shows that in only two other countries is payment by check still commonplace.

    And in both of those countries, check usage has fallen more sharply than in the United States.

    The value amounts are not adjusted for inflation, and the data is collected and released once every three years.

    Who uses checks today?

    While check payments have declined, there are still two big groups of check writers in the United States.

    The Federal Reserve Bank of Atlanta runs the Survey and Diary of Consumer Payment Choice. This survey asks people, rather than banks, for information on their payment habits. Roughly one-third of all respondents stated they used a paper check in the past 30 days.

    An older lady writes out checks to pay bills.
    Older Americans write more checks than younger people. Jupiterimages/The Image Bank via Getty Images

    Not surprisingly, the answers vary by age. About 60% of people 65 and over say they wrote a check. Among those 18 to 24, under 6% said they did.

    It also turns out that a lot of people who think they never write checks actually unknowingly do it all the time. If you pay your bills online, your bank tries to pay them electronically. If it cannot electronically make the payment, the bank cuts a paper check on your behalf. Any online bill payment taking more than a couple of business days to post is being sent by check.

    Another important factor is that small businesses love checks. Over 80% of businesses with sales between $1 and $10 million make payments using checks. Why? Small businesses often require two signatures on a check. The need for signatures means owners have to sign their name before any money goes out the door. This gives them control over money and a clear idea who is getting paid and how much.

    Small businesses also like receiving checks. I wrote a lot of checks after my mother’s death because many of those small businesses I dealt with wanted an extra 3% and sometimes more to cover the cost to them of a credit card payment. Writing paper checks saved me and the businesses a lot of money.

    The future

    While many Americans still write checks, their declining usage clearly underscores that they are not ideal for making payments in all situations.

    One of the biggest problems with checks is that you never know if the check writer has sufficient funds to cover the amount. When an account doesn’t have enough money, the check bounces. The Federal Reserve, which clears about one-third of all U.S. checks, returned about 22 million checks, with a total face value of around $80 billion. While these numbers are large, over 99% of all checks written don’t bounce.

    Another problem with checks is forgery. Thieves steal checks from mailboxes, alter information and then cash them. The most recent figures show about 500,000 annual cases of check fraud in the U.S. Again, while a half-million is large, it is a tiny fraction of the 9.2 billion checks written annually.

    Because of these problems, the Federal Reserve is contemplating leaving the check processing business. In early 2026, it accepted public comments on whether it should wind down, improve or leave alone its check processing unit.

    The unit, which costs about $100 million a year to run, turned a $6.6 million profit in 2024. But its machines need replacing, and the Federal Reserve is wavering on spending the money.

    Front and back of a U.S. half-cent coin.
    The U.S. government stopped minting its half-cent coin in 1857 due to its lack of usefulness. Mark Kostich/iStock via Getty Images Plus

    Should checks be killed off like the penny, which the federal government stopped minting in 2025, and the haypenny, which was worth half a cent and hasn’t been produced since 1857?

    For me, the answer is a clear no. While checks are clearly less important today than in the past, the numbers show that the American people and businesses still use and need checks.

    This article originally appeared on The Conversation. You can read it here.

  • The states with the highest rates of uninsured drivers and what it costs everyone else
    Photo credit: mojo cp // Shutterstock – An insurance agent explaining a policy to a customer.
    ,

    The states with the highest rates of uninsured drivers and what it costs everyone else

    Coverage gaps leave insured drivers and taxpayers footing the bill.

    Jeff Temple

    Nearly every state requires drivers to carry auto liability insurance, yet millions of motorists are still on the road without it.

    In 2023, 15.4% of U.S. drivers were uninsured, according to the Insurance Research Council, meaning more than 1 in 7 motorists lacked coverage that could pay for injuries or damage they caused in a crash. The rate has increased since 2017 and remains elevated after a pandemic-era jump that affected nearly every state.

    The burden is not limited to those driving without coverage. When an uninsured driver causes a crash, costs can shift to injured people, insured drivers, insurers, public systems, and households already dealing with higher auto insurance prices.

    Temple Injury Law, a Las Vegas personal injury law firm, examined national insurance and crash-cost data to understand where uninsured driving is most common and how those costs ripple beyond the crash scene.

    Mississippi, New Mexico, and D.C. had the highest uninsured-driver rates

    The highest uninsured-driver rate in 2023 was in Mississippi, where 28.2% of motorists were uninsured, according to the IRC. New Mexico followed at 24.1%, and the District of Columbia ranked third at 23.1%. At the other end of the spectrum, the lowest rates were in Maine at 5.7%, Utah at 6.2%, and Idaho at 6.4%.

    Those gaps show how differently the uninsured-driver problem plays out across the country. In Mississippi, the share of uninsured motorists was nearly five times Maine’s rate. Nationally, the National Association of Insurance Commissioners notes that uninsured-motorist rates range from 5.7% in Maine to 28.2% in Mississippi, despite near-universal legal requirements to carry coverage.

    The Insurance Research Council says several factors are associated with state-to-state differences, including economic conditions, insurance costs, and state insurance laws and regulations. That makes uninsured driving both a compliance issue and an affordability issue: A state can require insurance, but that does not guarantee every driver can afford or maintain it.

    Most states require insurance, but enforcement varies

    Auto liability insurance is compulsory in 49 states and the District of Columbia. New Hampshire is the only state without a compulsory auto insurance law, though drivers there must meet financial responsibility requirements in certain circumstances.

    Liability coverage is meant to protect other people when a driver causes a crash. But minimum coverage requirements vary by state, and so do enforcement systems. Some states use electronic insurance verification programs, registration checks, fines, license suspensions, or other tools to discourage uninsured driving. Others rely more heavily on proof-of-insurance checks after traffic stops or crashes.

    The result is a system in which uninsured driving can remain undetected until a collision occurs. By then, the financial problem has already moved from a compliance question to a question of who pays.

    The cost often shifts to insured drivers

    The NAIC describes uninsured motorists as a cost burden on drivers who comply with compulsory insurance laws. When uninsured drivers cause crashes, some of those costs are integrated into uninsured-motorist coverage purchased by insured drivers, which can help pay for injuries or vehicle damage caused by someone without insurance.

    That does not mean uninsured drivers are the only reason premiums rise. Auto insurance prices are affected by many factors, including accident rates, traffic density, vehicle theft, repair costs, medical and legal costs, population density, weather, and state liability requirements, according to the NAIC’s 2023 Auto Insurance Database report.

    Still, uninsured driving adds another layer of risk to an already expensive system. The NAIC reported that the countrywide average auto insurance expenditure was $1,281 in 2023, up 13.98% from the previous year. The countrywide combined average premium rose 14.41% to $1,438.

    For households living close to the edge, those increases can matter. In its 2023 household well-being survey, the Federal Reserve found that not all adults could cover an unexpected $400 emergency expense with cash or its equivalent, underscoring how a relatively small financial shock can force trade-offs for some families.

    Crash costs reach far beyond insurance claims

    The financial consequences of uninsured driving sit inside a much larger crash-cost system. The Bureau of Transportation Statistics estimated that motor vehicle crashes in 2019 incurred $340 billion in economic costs, including medical care, lost productivity, legal and court costs, emergency services, insurance administration, congestion, property damage, and workplace losses. Public revenues covered roughly 9% of all motor vehicle crash costs in 2019, amounting to about $30 billion, or $230 in added taxes for every U.S. household.

    Those figures are not limited to crashes involving uninsured drivers. But they help explain why insurance gaps matter: When the person responsible for a crash lacks coverage, the costs do not disappear. They are absorbed elsewhere. It can be through another driver’s insurance, out-of-pocket expenses, health coverage, legal systems, public services, or uncompensated losses.

    Underinsurance is growing, too

    Uninsured driving is only part of the problem. In 2023, 18% of U.S. drivers were underinsured, meaning they had liability insurance but not enough to cover the injury costs caused by a crash, according to the Insurance Research Council. Combined, IRC found that about 1 in 3 drivers was either uninsured or underinsured.

    That distinction matters for crash victims and insured motorists. A driver may technically comply with state insurance requirements and still carry limits too low to cover serious injuries, medical bills, lost income, or long-term care. IRC noted that rising underinsured-motorist rates are driven by upward pressure on the severity of bodily-injury claims.

    For drivers, the practical risk is similar: Even when another motorist has some insurance, the available coverage may fall short of the crash’s actual cost.

    What the numbers show now

    The latest public data points to a persistent national problem: Uninsured driving remains common, the highest-rate states have uninsured-driver shares above 20%, and underinsurance is rising alongside it.

    For insured drivers, the issue is not only whether another motorist is following the law. It is whether the financial safety net that is supposed to follow every vehicle on the road is strong enough when a crash happens. In states with the highest uninsured-driver rates, that safety net is missing for roughly one-quarter of motorists.

    This story was produced by Temple Injury Law and reviewed and distributed by Stacker.

Explore More Everyday Economics Stories

Money

Should paper checks be abolished like the penny?

Everyday Economics

The states with the highest rates of uninsured drivers and what it costs everyone else

Everyday Economics

5 things to do when the car’s check engine light comes on before spending money at the mechanic

Everyday Economics

Coloradans can now fight against a weaker economy and hunger through the ‘Tamale Act’