As prices are going up and are projected to keep rising, many people are looking for ways to save money, whether it’s on entertainment, services, or needs. It can be difficult to parse through what is truly saving you money versus what could be available to you for cheap, if not free. Thanks to the internet, there are some little known options out there that could help.

A community of consumers started a thread online discussing and sharing the websites that many people aren’t talking about but should. These websites provide a bunch of necessary services to either help people find the best deal, offer help on certain needs for free, or provide oodles of entertainment without you needing to pay a dime. Here are six of the recommended resources that can help stretch your wallet more during these economically trying times.

Camelcamelcamel.com

One of the cited websites for people who want to save even more money on their Amazon purchases was camelcamelcamel.com. The website can help consumers track the prices of products they buy to help see if there are any patterns to get the deal possible, which isn’t always during Prime Day. It’s free and you can sign up for the website to send alerts when a product is at a historically low price point.

StopOverpaying.org

One consistent, common expense is car insurance and it’s difficult to get straight answers on whether or not you’re getting a fair quote. Every provider has some quote calculator to go through and then you end up going to website after website. Consumers have found StopOverpaying.org to be a great resource to shop around for car insurance. For free, the website asks all the questions major auto insurance providers ask while automatically winnowing them down to the best offers available to you.

If you’re looking to buy a car to insure, consumers recommend carfinderzone.com for a free and thorough search of the makes and models you’re looking for.

Openstax.org

If you want to bone up on your studies for various tests and certifications, Openstax.org provides free access to learning resources and books for subjects from kindergarten to grade 12 along with college resources, too. As more parents in the United States choose to homeschool, this could be a valuable resource for accurate and accredited teaching materials that are up-to-date and free to use.

Ninite.com

If you’re curating various extensions and helpful apps on your computer or browser to replace ones you pay for, your first stop might want to be Ninite.com. The website is a free one-stop-shop for a person to connect and download popular apps like VLC, GIMP, Evernote, and other apps for imaging, video playback, online storage, Java, etc. from their official sources. This way you can save time by getting them all installed simultaneously rather than individually searching for and downloading the apps one by one while worrying about possible bad links or phishing scams. Plus, Ninite automatically updates the apps to ensure you’re getting the latest versions for free.

Photopea.com

Photoshop can be expensive if you don’t use it too often, and there are several “free” photo editing services available online, they usually block or limit editing choices to try to coax you into buying the full free version. Photopea.com allows you to use all of its photo editing features for free on your browser, only asking for money if you want an ad-free experience.

A library card

“A library card isn’t a website!” Well, technically, no, but it grants you access to several money-saving ones. One of the biggest bank account drainers are the various e-book and streaming services, and many consumers are looking for alternatives to prevent themselves from having too many monthly subscription charges. By getting a library card you can find thousands of e-books, movies, TV shows, and other forms of entertainment for absolutely free. Blockbusters, best sellers, and everything in between. First, there is Libbyapp.com that grants access to e-books, digital audiobooks, and magazines for free. For film buffs, Kanopy.com is a streaming service full of movies. If you want to make the most out of your library card, Hoopladigital.com has e-books, audiobooks, comics, movies, TV shows, and music to read or stream through your devices. No tricks, just supporting your local library is all that is asked to gain access to all of these websites (and, of course, physical libraries, too).


Every dime matters during times like these, so it’s great to share with one another great places to save online and beyond.

  • The tourism industry is slowly waking up to solo travelers’ needs
    Photo credit: Sebastien Goldberg on Unsplash – As more and more people live alone, solo travel is becoming increasingly popular.

    Solo travel is surging – and an industry still largely built for two is taking note.

    Google reported in April 2026 that online searches involving “solo travel” hit an all-time high this year, with queries for “women solo travel” reaching a 15-year peak. Hilton’s 2026 trends report found that 26% of travelers planned to take a trip alone this year, and that nearly half said they planned to add solo days to the front or back of a family trip.

    The issue isn’t new. In 1992, marketing researchers identified the solo consumer as an underserved market. But as tourism researchers have documented, the accommodation sector treats double occupancy as the default unit of consumption, which often slaps a “single supplement” charge on customers when they travel without a partner. The industry essentially penalizes travelers for arriving without a second body to fill the other half of a room they aren’t using.

    The reason why so many hotels, cruise lines and tour operators still base prices on double occupancy is that their costs – the room, the berth, the coach seat, the guide – don’t fall by half when the second person fails to materialize. But the supplement isn’t just a pricing convention. It’s the clearest signal the industry sends about who it built the product for.

    I’m a scholar who studies what I call the solo economy: how institutions and markets adapt, or fail to adapt, to the rise of single living. I’ve written before about how retail and restaurants still design for pairs.

    Travel is further along than most in recognizing this cultural shift. It’s also a useful case because the industry has started on the easy part of the problem but barely touched the rest.

    Demographics matter, but not the way you’d think

    The broader shift toward solo living is real. In 2025, 39.7 million Americans lived alone. That’s 29% of all households, up from 20% in 1975. Married couples, meanwhile, fell to 47% of households from 66% 50 years earlier.

    Those numbers alone don’t explain solo travel. Some of that decline went to people living alone; some went to unmarried couples, who are still a party of two on a booking page. Married people take trips alone. Single people travel with friends, siblings and parents, and plenty of them have logged serious hours as an extra wheel. Living alone and vacationing alone are different behaviors with different causes.

    What connects them is the erosion of a single assumption: that every adult arrives with a plus-one. That assumption is weakening at home, and it’s now encountering the booking page.

    Price is the easy rung

    One response by the travel industry has been to shave the single supplement. For example, the tour operator Tauck announced this year that it’s waiving the single supplement on a class of its riverboat cabins across more than 250 European river cruise departures and reducing it by up to US$600 on 105 land departures.

    Another touring company has taken a more committed approach to adjusting its offerings: Aurora Expeditions sets aside 10 dedicated solo cabins on every sailing across its three ships, with no single supplement, through its 2026 and 2027 seasons.

    Then there’s Norwegian Cruise Line, which was early to the shift. In 2010, it introduced Studio staterooms aboard Norwegian Epic: Small cabins designed for one passenger, sold at single-occupancy prices and arranged around a keycard-access Studio Lounge reserved for solo travelers. The trade-off is less private space, but at a price for one, with access to a room full of fellow travelers going it alone.

    Norwegian then expanded solo categories in 2024 from nine ships to its full 19-ship fleet. But on ships without Studios, much of the expansion was relabeling. Cruise Critic reported that standard double-occupancy rooms would likely be reclassified rather than retrofitted. And by Norwegian’s own account, the Studio Lounge is reserved for guests in Solo Studios – so the fleetwide solo categories come with the discount but not the room full of other solo travelers.

    That’s the difference between repricing and redesigning. The 2010 Studio was a purpose-built 100-square-foot (9 square-meter) cabin that cost Norwegian something to construct. The 2024 categories are, in many cases, the same rooms as before, with a new label and a discount. The solo traveler pays less than two people would, but it’s still more than half for a room sized and built for two. A cabin sold to one occupies the same space as a cabin sold to two, and the industry still counts berths.

    There’s a cleaner approach. Yotel sells a room type it calls Solo – 114 square feet (about 10 square meters) in New York City, maximum occupancy one, at the bottom of its price range. Nothing was subtracted to make it. It was built at that size, for that guest, and priced accordingly. That’s what designing for one looks like, and it’s rare enough that a tiny room counts as progress.

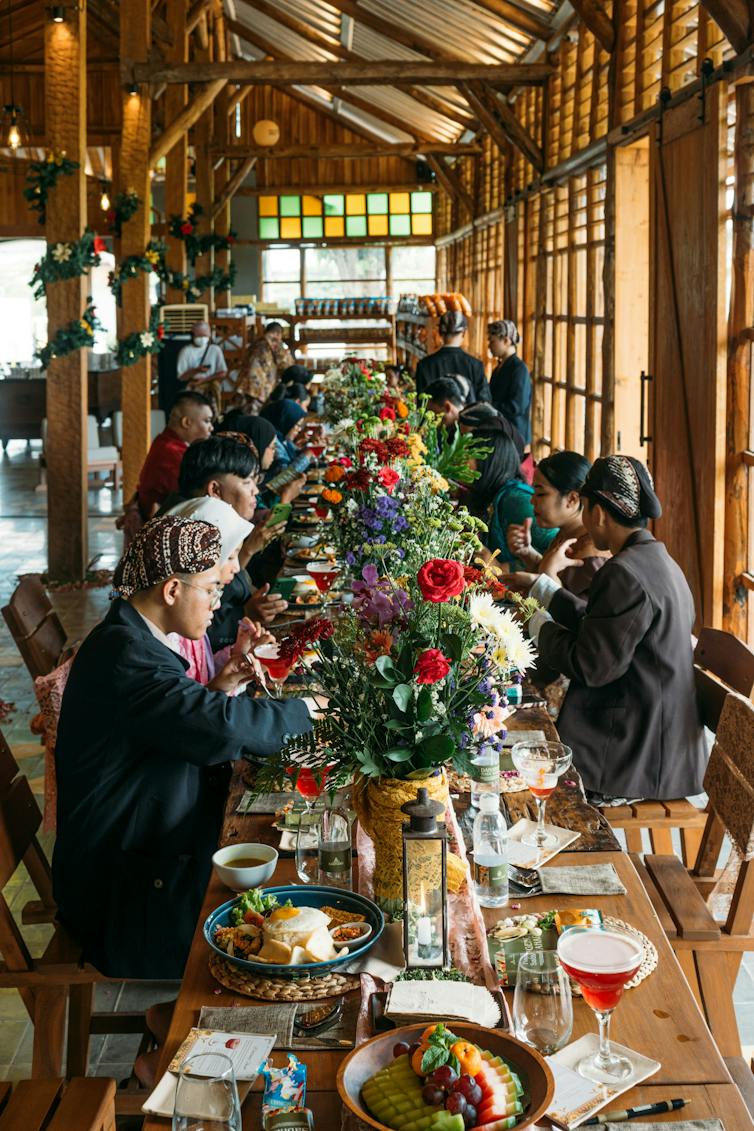
    At a long table covered by flowers and plates of food, a diverse group of travelers shares a meal.
    Many solo travelers seek control over their experiences and schedules, but they still seek a social component. Keriliwi on Unsplash

    Traveling alone doesn’t mean being alone

    A common mistake in designing for solo travelers is assuming that solitude is the product. It isn’t.

    In the same 2026 data showing record interest in solo travel, Google found that searches for “travel groups” and “tour groups” also hit record highs. A Mastercard survey of more than 15,000 consumers across 11 countries found that 39% of international travelers had already taken a trip alone — and 7 in 10 international leisure travelers were interested in solo experiences built to connect them with like-minded people.

    The contradiction makes sense when you acknowledge that privacy and isolation are two different things. A person can want total control over where to go, when to eat and when to return to the room – and still want company at dinner.

    The issue with double-occupancy pricing is that it assumes the customer brings their own company. But when only one person books, the operator has to address the pricing problem – whether or how to discount; and a product problem – how to supply a social component. Waiving a solo supplement solves the first issue, but it ignores the second. Norwegian understood this in 2010 by creating its lounge for solo travelers.

    The pitch is easier when the product is for one

    For all these changes, travel advertising often still runs on couples: two glasses of wine, two lounge chairs, two silhouettes against a sunset. Sandals Resorts built an entire resort category around the premise.

    When solo travel does appear, it gets a different script. The traveler is adventurous, on a journey of self-discovery. AARP’s current solo-travel guide emphasizes personal growth and self-reliance. Even Norwegian closes its solo pitch by reassuring the reader that “you’re pretty good company.”

    The effect is to mark solo travel as exceptional at precisely the moment it stops being exceptional. Nobody reassures a couple that they will enjoy the balcony. Calling a solo traveler “brave” can be a compliment, but it can also reveal the assumption that traveling alone is abnormal, even when that’s changing.

    That all said, parts of the tourism industry have taken big steps over the past 15 years. But treating solo travelers as an audience rather than an accommodation is harder. It’s about selling them what they have already said they want: control over the trip, and access to other people, on their own terms.

    Marketing researchers named this opportunity in 1992. Thirty-four years later, the industry is still learning to build for one. Meanwhile, the solo traveler is standing at reception, holding a credit card, waiting for someone to design a room.

    This article originally appeared on The Conversation. You can read it here.

  • Should paper checks be abolished like the penny?
    Photo credit: CSA Images/Getty Images – While Americans are writing fewer checks, they haven’t abandoned this means of payment.
    ,

    Should paper checks be abolished like the penny?

    Billions are still written each year, even as digital payments take over.

    Germany is getting rid of paper checks at the end of 2027. Australia is bidding them farewell by 2030. U.S. President Donald Trump followed up his order killing off the penny with an executive order stopping check writing by the federal government.

    Should the U.S. follow these other countries and broadly eliminate the ability to write checks?

    Years ago, experts predicted that checks would have disappeared by now. However, they are still around, and billions are written each year in the United States.

    Why? The quick answer is that businesses love them. And plenty of Americans still use checks for good reasons. But there is more to the story.

    I am a business school professor and one of the few academics who advocates for the use of cash. While I have long told everyone about the benefits of paper money, I didn’t give paper checks much thought or use them until my mother’s recent death. Then I found myself writing checks to the cemetery, funeral home, gravestone engraver and a host of other places. Plus, I started getting refund checks back from her landlord and insurance companies.

    These experiences made me look more deeply into this form of payment to understand what was happening.

    Fewer checks for bigger bucks

    Every three years the U.S. government runs the Federal Reserve Payments Study by asking banks and credit unions for internal information. This survey tracks everything from how often credit cards are used to the number of checks written.

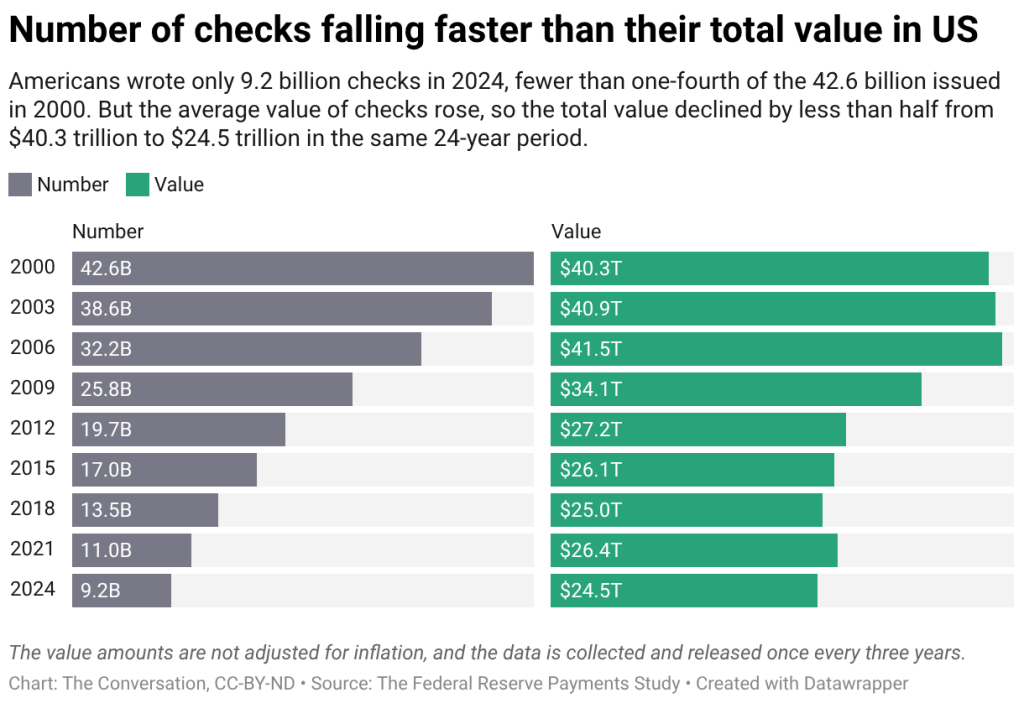
    While check usage has sharply declined in the U.S., a significant number – about 9.2 billion in 2024 – are still written, the data shows. The face value of those checks is probably bigger than you’d expect: more than US$24 trillion, not adjusted for inflation. That is almost as large as U.S. gross domestic product of $29 trillion that year.

    Not everyone can imagine numbers in billions or trillions, so let’s put those figures in more manageable terms.

    A little over 150 checks were written per person in 2000. By 2024, the average had plummeted to 27 checks – slightly more than two per month. However, over that time, the amounts typically scribbled or printed on the face of those checks rose.

    In 2000, the typical check was worth less than $1,000. By 2024, the average amount had more than doubled to $2,600.

    Trends elsewhere are similar. The Bank for International Settlements, which serves as a bank for central banks like the Federal Reserve, has tracked check usage in 25 countries since 2012. Its data shows that in only two other countries is payment by check still commonplace.

    And in both of those countries, check usage has fallen more sharply than in the United States.

    The value amounts are not adjusted for inflation, and the data is collected and released once every three years.

    Who uses checks today?

    While check payments have declined, there are still two big groups of check writers in the United States.

    The Federal Reserve Bank of Atlanta runs the Survey and Diary of Consumer Payment Choice. This survey asks people, rather than banks, for information on their payment habits. Roughly one-third of all respondents stated they used a paper check in the past 30 days.

    An older lady writes out checks to pay bills.
    Older Americans write more checks than younger people. Jupiterimages/The Image Bank via Getty Images

    Not surprisingly, the answers vary by age. About 60% of people 65 and over say they wrote a check. Among those 18 to 24, under 6% said they did.

    It also turns out that a lot of people who think they never write checks actually unknowingly do it all the time. If you pay your bills online, your bank tries to pay them electronically. If it cannot electronically make the payment, the bank cuts a paper check on your behalf. Any online bill payment taking more than a couple of business days to post is being sent by check.

    Another important factor is that small businesses love checks. Over 80% of businesses with sales between $1 and $10 million make payments using checks. Why? Small businesses often require two signatures on a check. The need for signatures means owners have to sign their name before any money goes out the door. This gives them control over money and a clear idea who is getting paid and how much.

    Small businesses also like receiving checks. I wrote a lot of checks after my mother’s death because many of those small businesses I dealt with wanted an extra 3% and sometimes more to cover the cost to them of a credit card payment. Writing paper checks saved me and the businesses a lot of money.

    The future

    While many Americans still write checks, their declining usage clearly underscores that they are not ideal for making payments in all situations.

    One of the biggest problems with checks is that you never know if the check writer has sufficient funds to cover the amount. When an account doesn’t have enough money, the check bounces. The Federal Reserve, which clears about one-third of all U.S. checks, returned about 22 million checks, with a total face value of around $80 billion. While these numbers are large, over 99% of all checks written don’t bounce.

    Another problem with checks is forgery. Thieves steal checks from mailboxes, alter information and then cash them. The most recent figures show about 500,000 annual cases of check fraud in the U.S. Again, while a half-million is large, it is a tiny fraction of the 9.2 billion checks written annually.

    Because of these problems, the Federal Reserve is contemplating leaving the check processing business. In early 2026, it accepted public comments on whether it should wind down, improve or leave alone its check processing unit.

    The unit, which costs about $100 million a year to run, turned a $6.6 million profit in 2024. But its machines need replacing, and the Federal Reserve is wavering on spending the money.

    Front and back of a U.S. half-cent coin.
    The U.S. government stopped minting its half-cent coin in 1857 due to its lack of usefulness. Mark Kostich/iStock via Getty Images Plus

    Should checks be killed off like the penny, which the federal government stopped minting in 2025, and the haypenny, which was worth half a cent and hasn’t been produced since 1857?

    For me, the answer is a clear no. While checks are clearly less important today than in the past, the numbers show that the American people and businesses still use and need checks.

    This article originally appeared on The Conversation. You can read it here.

  • Millions of Illinois residents wake up to find that $2.6 billion of their medical debt has been eliminated
    Photo credit: Canva – Millions in Illinois had their medical debt paid for.

    Regardless of how well or poorly the overall economy is doing, many Americans are saddled with crushing medical debt. Such debt can hold people in a dangerous place: they can’t prosper or build wealth because they’re too deep in the hole, and they might make their health worse by forgoing necessary care in order to save. However, one million residents in Illinois are breathing a sigh of relief knowing their medical debt has been paid for.

    Partnering with officials in Cook County and Undue Medical Debt, Illinois Gov. J.B. Pritzker worked on the Illinois Medical Debt Relief Program based on a Cook County Medical Debt Relief Initiative. The patients needn’t apply for the relief initiative; they just had to be Illinois residents with a household income at or below 400% of the federal poverty level. They could still qualify if they had medical debts equal or more than 5% of their annual household income. If qualified, the resident would receive a confirmation letter that their debt had been paid.

    Debt today, gone tomorrow

    “In Illinois, we believe healthcare is a human right—and affordability is central to that promise,” Lieutenant Gov. Juliana Stratton said in a press release. “No one should ever delay care because of cost or face financial ruin simply because they got sick. The Illinois Medical Debt Relief Program is about lifting that burden, strengthening families, and ensuring every Illinoisan can seek the care they need. When we make healthcare more affordable, we build healthier and stronger communities.” 

    “Combined with our partners here in Cook County, who have erased $1.5 billion, we have delivered more than $2 billion in relief to over a million Illinoisans in all 102 counties of our state, with an average elimination across the state of $1,200 per patient,” Pritzker told The Center Square.

    Another state collaboration with Undue Medical Debt

    If this story sounds familiar, GOOD recently covered the state of Connecticut partnering with Undue Medical Debt in a similar fashion. To put it simply, the strategy UMD and their partners use is to purchase medical debt from bill collectors. They bundle and purchase the debt for a discount and, since they are buying so much debt at once, they’re typically able to negotiate a good deal. This means that they’re able to purchase most debt for pennies on the dollar.

    It’s not without critics

    While this has been bringing relief to many folks, there are still critics. A 2024 National Bureau of Economic Research study found that medical debt erasure didn’t improve the recipients’ overall financial well-being. While no longer having medical debt relieves a burden, it doesn’t automatically raise a person’s wages, assist housing needs, etc. 

    They also argue that having medical debt relieved wouldn’t improve a person’s access to healthcare. A patient may accrue new, additional debt because of ongoing care. A person may also still avoid getting necessary care to avoid a new bill.

    It will be interesting to see if this version of medical debt relief becomes even more common or if different solutions are inspired from it.

Explore More Money Stories

Money

Should paper checks be abolished like the penny?

Money Culture

Millions of Illinois residents wake up to find that $2.6 billion of their medical debt has been eliminated

Everyday Economics

The states with the highest rates of uninsured drivers and what it costs everyone else

Smart Spending

South Korea creates a website that allows you to pretend to order takeout to get the dopamine rush without spending a dime